


Written by Ethan Walker, JD, Fintech Associate
Reviewed by Pouya Makki, JD, Head of Fintech Practice
Last Updated: October 21, 2026
# US vs Canada MSB Regulations: The Key Differences
Our mission is to help Canadian fintech companies get registered, go live, and stay compliant.
The cleanest way to understand US and Canada MSB regulation is to see that each country runs two separate layers. The first is a federal anti–money laundering (AML) layer, run by a national financial-intelligence unit. The second is a risk management layer — the prudential rules that focus on operating safely and protecting customer funds. The big structural difference is where that second layer sits: in Canada it is federal, under the Bank of Canada; in the US it is state-by-state, through a money transmitter license (MTL) in each state.
A money services business (MSB) is a business that moves, exchanges, or deals in money or virtual currency for other people. Below we compare the two systems layer by layer: who runs the AML layer, who runs the risk management layer, what triggers each, and how crypto, penalties, and banking differ. If you want help registering specifically in Canada, see our Canadian MSB registration page.
2026 Update: what changed
This guide was rewritten as a direct US-vs-Canada comparison. Key updates: we reframed the comparison around two layers in each country — a federal AML layer and a separate risk management layer (federal in Canada under the RPAA, state-by-state in the US through money transmitter licenses); clarified that FINTRAC MSB registration is a registration, not a licence; added Quebec's separate provincial MSB licence (now administered by Revenu Québec); and refreshed the penalty and crypto sections.
Canada vs US MSB regulation at a glance
Use this table as the quick comparison, then read on for the detail that matters for your model. Canada runs one broad federal AML regime plus a separate federal risk management regime, while the US splits oversight between one federal registration and risk management licensing in nearly every state for certain payment companies.
| What it covers | Canada | United States |
|---|---|---|
| AML layer — regulator | FINTRAC (federal), under the PCMLTFA | FinCEN (federal), under the Bank Secrecy Act (BSA) |
| AML layer — trigger | Carrying on an MSB activity: money transfer, currency exchange, or dealing in virtual currency | Same idea: acting as a money transmitter or other MSB for AML purposes |
| Risk management layer — regulator | Bank of Canada (federal), under the Retail Payment Activities Act (RPAA) | Each state's regulator — no federal equivalent |
| Risk management layer — trigger | Helping a client send funds to, or receive funds from, a third party — even if you never hold the funds | Generally taking control of customer funds (money transmission) |
| Minimum capital and surety bonds | No prescribed minimum capital or net worth, and no general licensing surety-bond requirement under the RPAA. PSPs holding end-user funds must still safeguard them through a trust account, or a segregated account backed by insurance or a guarantee. | State MTLs generally require minimum net worth and a surety bond; amounts vary by state and may depend on transaction volume. The bond’s coverage amount is not its annual premium, and collateral may also be required. |
| Ongoing regulatory and compliance costs | Bank of Canada annual assessment fees, operational risk framework maintenance, reporting and compliance work, plus safeguarding costs if you hold end-user funds. Insurance or guarantee costs can apply if you choose that safeguarding option. | State renewal or assessment fees, NMLS fees, annual bond premiums, audited financial statements and ongoing compliance work; examination charges may also apply. Total costs depend on the states covered, transaction volume and bond underwriting. |
| Extra sub-national layer | Quebec requires its own provincial MSB licence on top of FINTRAC | ~49 states + DC and territories each license separately |
| Crypto | Certain crypto activities may trigger FINTRAC MSB registration and some others may trigger securities registration | Certain crypto activities may trigger FinCEN MSB registration; some crypto companies may additionally need state by state MTL licensing in certain states; some states may require additional state licensing in addition to MTL licensing (e.g., NY BitLicense) |
| Local presence | FINTRAC and banks may expect a real Canadian presence | Varies by state |
What are the core differences between US and Canada MSB regulation?
There are two core differences. The first is structure: both countries have a federal AML regulator, but the risk management regulator is federal in Canada (the Bank of Canada) and state-by-state in the US (a money transmitter license in each state). The second is the risk management trigger. In the US, that layer generally follows control of money: if you accept funds from one person and pay them out to another, you are a money transmitter. In Canada, it is wider — generally helping a client send funds to, or receive funds from, a third party can require registration even if you never hold or touch the money. Same product, two different answers.
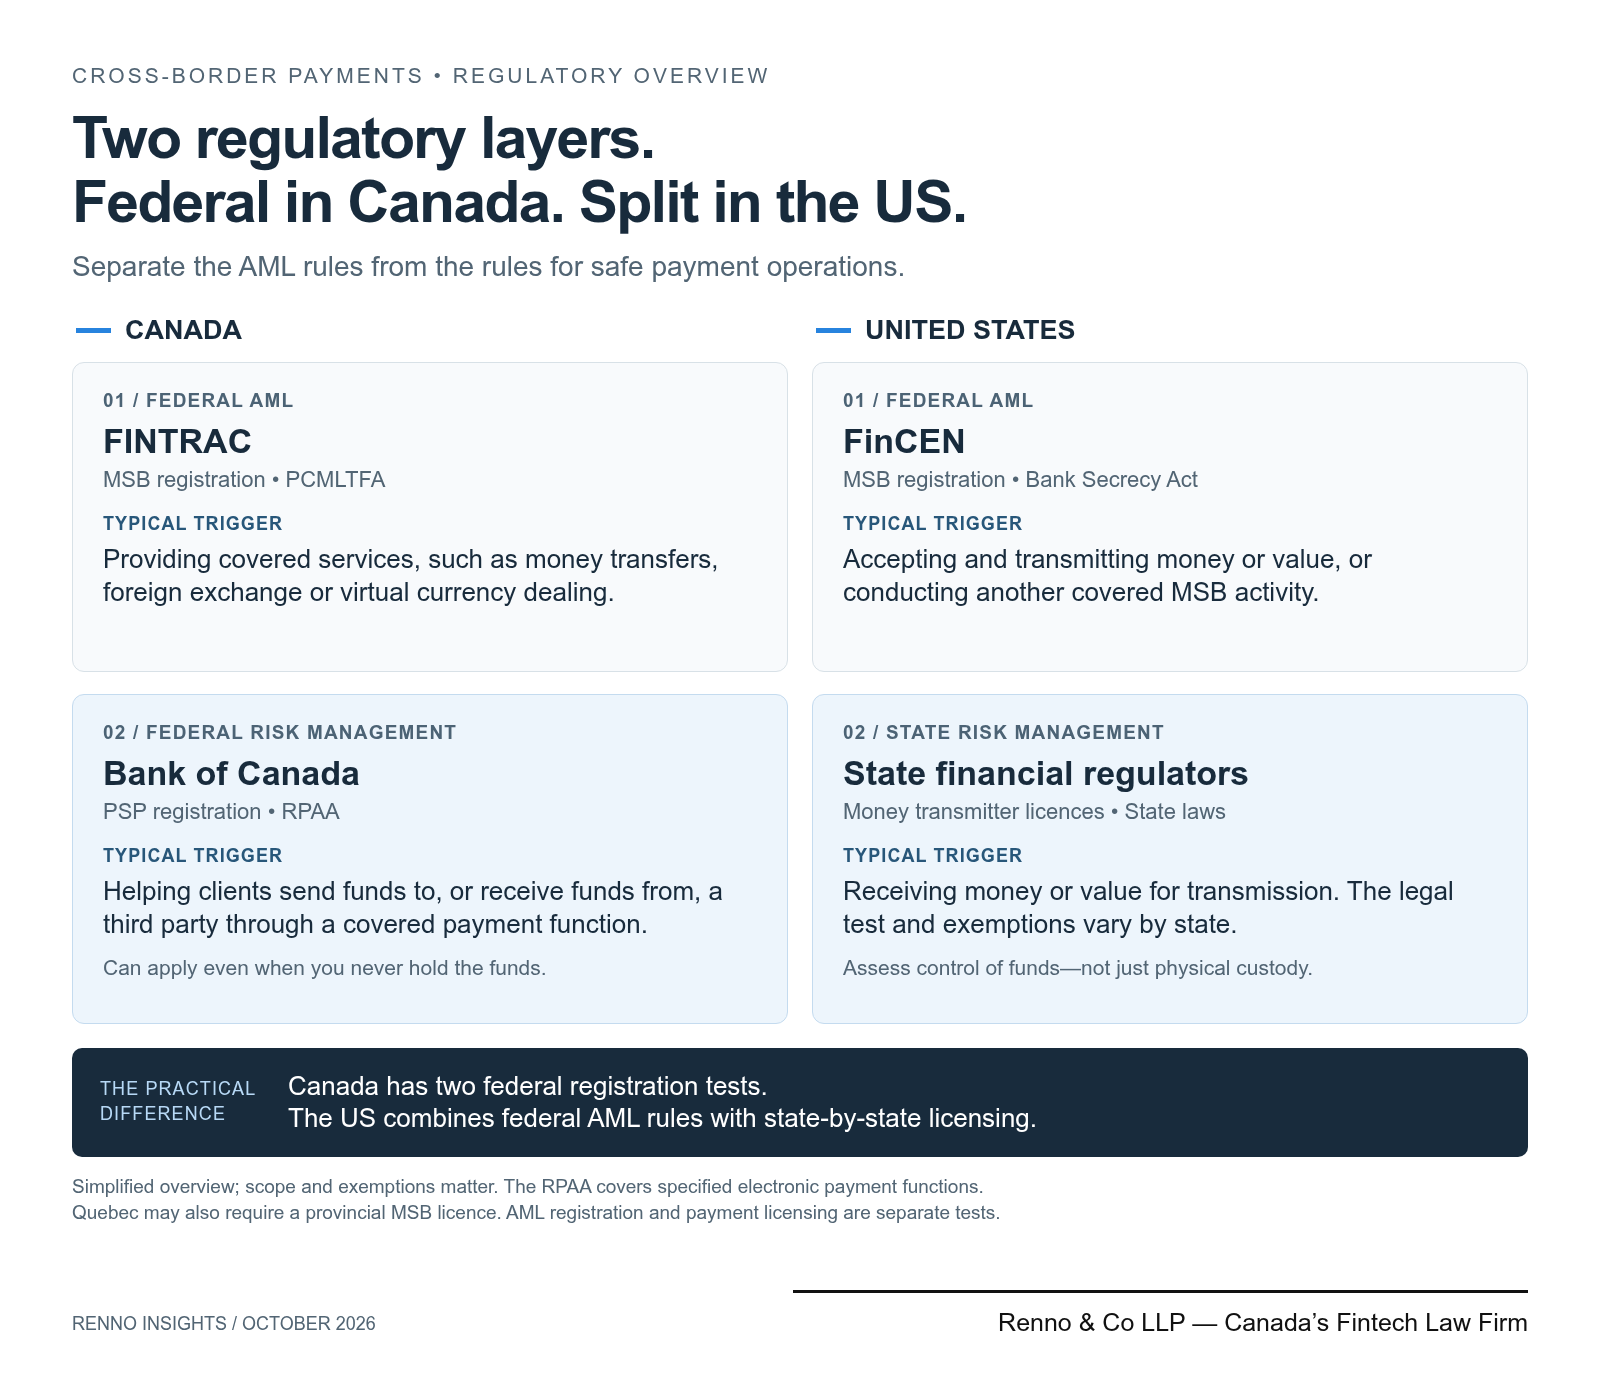
Two regulatory layers: US vs Canada
Regulatory layerCanadaUnited StatesFederal AMLFINTRAC
PCMLTFA registrationFinCEN
BSA registrationOperational risk / licensingBank of Canada
Federal RPAA oversightState regulators
Money transmitter licensing
Different thresholds and exemptions apply to each regime.
Two regulatory layers: federal AML registration in both countries, with federal RPAA oversight in Canada and state-by-state money transmitter licensing in the US. Each regime has its own scope and exemptions.
Consider a hypothetical fintech we'll call Streampay. Streampay is a US pay-by-bank company that operates across 48 states and Puerto Rico without any money transmitter licences. It never holds customer money — it only sends payment instructions to its bank partners, which move the funds. For purposes of this example, assume Streampay qualifies for the relevant US exemptions, so its non-custodial setup does not require FinCEN registration or a state MTL. That conclusion must be checked against the company's actual activities and each applicable jurisdiction.
Then Streampay looked at Canada to serve a few regulated, higher-risk sectors. The surprise: the identical instruction-only model can trigger both FINTRAC MSB registration and Bank of Canada registration under the Retail Payment Activities Act (RPAA) — plus a separate step for Quebec. What needs no licence in 48 US states can require two Canadian registrations.
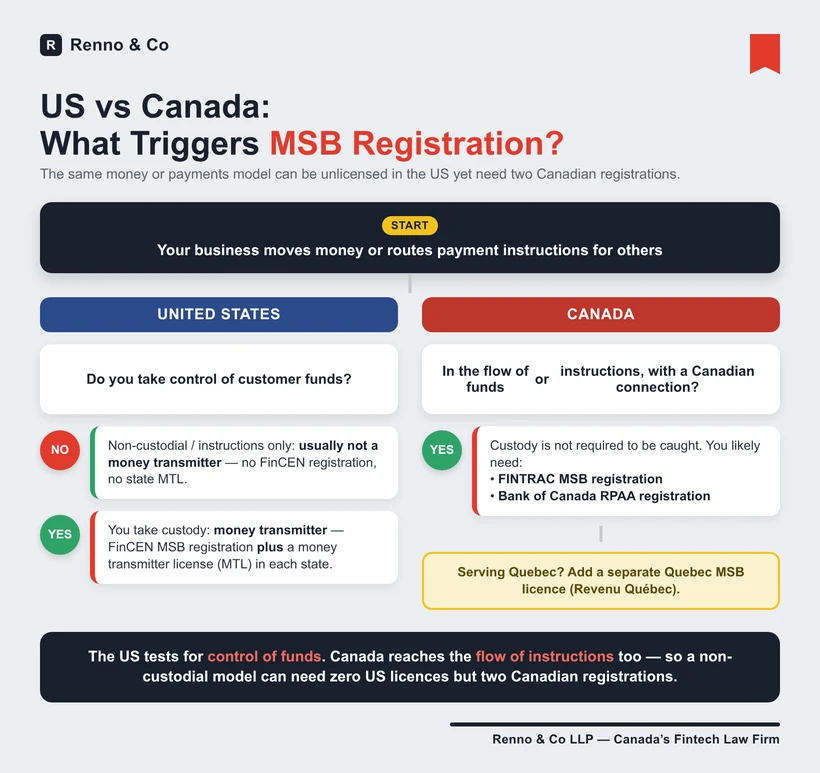
Payment instructions: regulatory decision map
Does your fintech facilitate customer payments without holding the funds?
United StatesCanadaAssess FinCEN's money transmitter definition, payment-processor exemptions and each state's money-transmission rules. Non-custodial operation alone does not conclusively settle the analysis.Assess FINTRAC MSB status and Bank of Canada RPAA registration independently. Even an instruction-only model can trigger RPAA obligations. Assess Quebec MSB licensing separately.
Illustrative analysis only. Coverage depends on activities, jurisdiction, and exemptions.
Decision tree: the US tests for whether you take control of customer funds, while Canada reaches the flow of funds or payment instructions and often requires both FINTRAC MSB registration and Bank of Canada RPAA registration, plus a separate Quebec MSB licence.
Layer 1 — the AML regulator: FINTRAC vs FinCEN
Both countries use a federal financial-intelligence unit. In Canada, that is FINTRAC (the Financial Transactions and Reports Analysis Centre of Canada), which administers the Proceeds of Crime (Money Laundering) and Terrorist Financing Act (PCMLTFA). In the US, it is FinCEN (the Financial Crimes Enforcement Network), which administers the Bank Secrecy Act (BSA). The jobs rhyme; the structure around them does not.
The real split is below the federal level. FINTRAC is Canada's single federal registrar for MSBs, so one registration covers the whole country — with Quebec as the exception discussed below. In the US, FinCEN registration sits on top of a state-by-state licensing system, where the heavy compliance work actually happens.
How does MSB registration differ in Canada and the US?
In Canada, you complete one FINTRAC MSB registration before you operate, and it is free. In the US, you file FinCEN Form 107 within 180 days of starting, renew every two years, and it is also free — but federal registration is only the entry ticket. The licensing burden lives at the state level.
Two points matter for legal accuracy. First, FINTRAC MSB registration is a registration, not a licence: the registry itself notes that being listed does not mean FINTRAC endorses or approves the business. The US FinCEN MSB is also a registration and not a license. Second, in the US a federal filing does not authorize you to transmit money anywhere — each money transmitter license (MTL) is granted by an individual state, typically with surety bonds, minimum net worth, and its own examinations.
Does Canada really have just one registration?
Almost. For MSB purposes, Canada is federal-only — except Quebec. A business serving Quebec generally needs a separate provincial MSB licence in addition to FINTRAC registration. So Canada is not purely "one-and-done," and the US is not uniformly "50 licences"; both have a federal layer plus sub-national licensing that depends on where you operate.
Quebec runs its own regime under the Money-Services Businesses Act (MSBA). Administration of that licence moved from the AMF to Revenu Québec in 2021. This is exactly why Streampay was told to treat Quebec as a separate workstream: a Canada-wide plan is not complete until Quebec is handled on its own track.
Layer 2 — the risk management regulator: RPAA vs state money transmitter licenses
This is the second layer, and it works very differently on each side of the border. In Canada it is federal: the Retail Payment Activities Act (RPAA), administered by the Bank of Canada, regulates payment service providers for operational risk and safeguarding of funds. Its trigger is broad — helping a client send funds to, or receive funds from, a third party (initiating or facilitating an electronic funds transfer) counts, even if you never hold the funds. In the US there is no federal version of this layer; instead, each state runs its own regime through a money transmitter license, and the trigger is generally narrower — you need an MTL when you transmit money on their behalf and take control of customer money as a part of your service offering. A non-custodial structure can affect the US money-transmission analysis but is not a universal exemption; the same model can still be caught in Canada.
This is the Streampay problem in one line: in the US, an instruction-only provider may avoid money transmitter requirements depending on its actual activities and applicable exemptions; in Canada, that same routing role is a retail payment activity that can require Bank of Canada registration, and the related money movement can require FINTRAC MSB registration too. The US rule turns on custody; the Canadian rule reaches the flow of instructions. You can read the Bank of Canada's own view in its criteria for registering payment service providers.
How do AML, reporting, and penalties compare?
The AML goals are similar; the mechanics and the stakes differ. Both regimes require a risk-based AML program, KYC, five-year record-keeping, and reporting of suspicious and large transactions. The US adds a federal timing rule — large currency transactions are reported on a set deadline — while Canada layers detailed electronic funds transfer and large virtual currency reporting on top of its suspicious-transaction regime.
Penalties are where the divergence shows. In Canada, FINTRAC issues tiered administrative monetary penalties (AMPs), and enforcement has climbed sharply in both frequency and size; penalties are also set to rise substantially under pending Budget 2025 legislation. In the US, failing to register as an MSB carries a civil penalty of up to $5,000 per violation, while willful BSA breaches can bring criminal exposure of up to $250,000 and five years' imprisonment.
How is crypto treated: Canada vs US?
Both countries treat many crypto businesses as MSBs. In Canada, dealing in virtual currency is an MSB activity, so crypto exchanges and dealers register with FINTRAC. In the US, FinCEN treats virtual currency exchangers and administrators as money transmitters, so they register federally — and crypto payment processors do not get the payment-processor exemption.
The difference, again, is the state layer. A US crypto business may need an MTL in each state where it serves customers (although there are certain states this may not be required in), and some states add a crypto-specific regime — New York's BitLicense being the best known. Canada keeps crypto inside the same federal MSB framework (with provincial securities rules reserved for custody and investment-like models), which is more uniform than navigating dozens of separate state authorizations.
What about Canadian presence and banking?
Two practical realities catch US fintechs off guard. First, both FINTRAC and most Canadian account providers expect a genuine Canadian presence and a working AML program — a mailbox address and a registration number are rarely enough. Second, getting registered is only half the job; securing banking or payment rails is often the hardest part of going live.
Many MSBs clear registration and then stall for months trying to open a bank account for a Canadian MSB, because banks scrutinize ownership, AML controls, and real operational substance. If you are weighing a Canadian footprint or worried about banking, book a call and we'll pressure-test your presence and AML setup before you file.
Expanding across the border
This article compares the two systems; it does not cover the full cross-border build-out. If you specifically want to know what a Canadian MSB must do to serve US customers, that is a different question, answered in our guide on how a Canadian MSB can serve US clients. For a broader view of standing up in Canada, see our guide to entering the Canadian market.
The takeaway from Streampay holds for most US fintechs looking north: do not assume your US licensing analysis carries over. Map your flow against the Canadian triggers first, because a model that is unregulated across most of the US can require FINTRAC registration, Bank of Canada registration, and a separate Quebec licence.
FAQs
What is the FINTRAC equivalent in the US?
FinCEN, the Financial Crimes Enforcement Network. It is the US federal financial-intelligence unit and administers the Bank Secrecy Act, much as FINTRAC administers the PCMLTFA in Canada. The key difference is that FinCEN registration sits alongside state money transmitter licensing, while FINTRAC registration is federal and covers Canada (with Quebec as a separate provincial exception).
Is FINTRAC MSB registration a licence?
No. It is a registration. Being listed on the FINTRAC registry does not mean FINTRAC approves, endorses, or vets the business — only that it has met the legal requirement to register. Calling it a "FINTRAC licence" is a common but inaccurate shorthand. Quebec, by contrast, issues an actual MSB licence under its provincial regime.
Can a US non-custodial payment company operate in Canada without registering?
Usually not. If a US company never takes control of funds, it often sits outside US money transmission. But Canada's RPAA can capture the flow of payment instructions, and the underlying money movement can trigger FINTRAC MSB registration — so the same model frequently needs both Canadian registrations, plus a Quebec licence if it serves Quebec.
Do I need to register in every Canadian province?
No. FINTRAC MSB registration is federal and covers the whole country. The one exception is Quebec, which requires its own provincial MSB licence on top of FINTRAC registration. This is the opposite of the US, where federal registration is the baseline and most of the licensing happens state by state.
Talk to us before you file
If you are a US fintech weighing a move into Canada, the smartest first step is to map your exact flow against the Canadian triggers — MSB, RPAA, and Quebec — before you commit to a structure or a timeline. We do this every week for payments and crypto companies. Book a call to review your model, confirm which registrations actually apply, and avoid filing for the wrong thing.
This content is for informational purposes only and does not constitute legal advice.
Ready to get started?
Talk To UsBook a Free Consultation
Speak with our fintech legal advisor
about your registration


